myWisely: Mobile Banking

Screenshots
Details
- Rating
- 12.12K reviews
- Version
- 26.6.0
- Developer
- ADP, INC.
Analysis by Norviv
Managing money on a phone sounds simple until an app gives you too many screens, unfamiliar labels, and no clear idea of what to do first. I found myWisely: Mobile Banking easier to approach when I treated it as a practical everyday finance tool rather than a complete replacement for every banking service. Its focus is straightforward: helping you receive pay, watch spending, and build better saving habits from one mobile account.
That focus makes it especially relevant if your employer uses a Wisely payment arrangement or if you want a dedicated place for regular spending. The app is free, aimed at Everyone, and developed by ADP, INC. It belongs to the finance category, but it does not feel like a complicated investment dashboard. I would describe it as a money-management companion for routine decisions: checking what is available, following transactions, and creating more awareness around where your money goes.
What to expect before you begin
The first thing I would tell a new user is not to expect the same experience as a traditional bank app. A conventional banking app may bring together checking, savings, loans, transfers, bill pay, and a large collection of account tools. myWisely is more focused. That narrower purpose can be a benefit because the important daily actions are easier to identify, but it also means it may not satisfy someone looking for a broad financial hub.
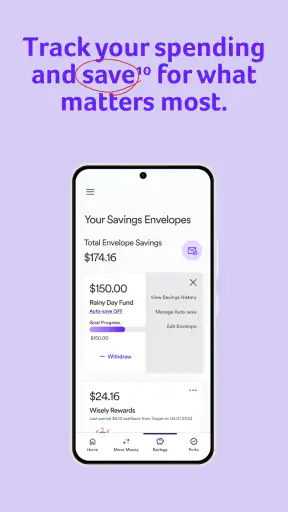
The app’s store summary, “Get paid. Track spend. Save more,” gives a useful picture of its intended rhythm. You check incoming money, review purchases, and use the information to make the next decision. In my experience, that sequence is more helpful than opening a finance app only when something goes wrong. A quick review after a purchase can prevent a small misunderstanding from becoming a larger budgeting problem.
Its public reception is encouraging, with an average rating of 4.3 from around 31 thousand ratings and roughly 12 thousand written reviews. More than 5 million installs also show that it is not an obscure experiment. Those figures do not guarantee that every person will find the service suitable, though. Finance apps depend heavily on the user’s employer, payment arrangement, personal habits, and expectations about banking.
One practical advantage is that the app is free to install. That removes an easy barrier for someone who wants to test the interface before deciding whether it fits their routine. I still recommend approaching the setup carefully. Free does not mean every financial situation will work identically, and an app connected to pay or spending deserves more attention than a casual social download.
The current version is 26.6.0, and the app requires at least OS 10. If your phone is older than that requirement, checking compatibility before spending time on registration is sensible. On a supported phone, the most useful first goal is not exploring every menu. It is completing one meaningful action, such as confirming that your available money and recent activity are visible.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Who will get the most from it
I see the strongest fit for people who want a clear mobile view of everyday funds without learning a full budgeting system. It can be useful for someone receiving wages through a supported Wisely arrangement, a worker who wants to separate spending money from other accounts, or a person who tends to lose track of small purchases. It may also suit a first-time finance-app user who prefers a focused interface over a long list of banking products.
The app is less convincing for someone who needs detailed investment analysis, complex household budgeting, or a single place for many unrelated financial accounts. If your main goal is comparing funds, managing a mortgage, or planning taxes, a specialist service will usually be better. Likewise, if you already have a bank app that handles your pay, spending categories, savings goals, and transfers exactly as you need, adding another app may create duplication rather than clarity.
Starting setup without making it harder than necessary
When I install a finance app, I prefer to prepare before opening it. I make sure I can access the email address or phone details associated with the account, confirm that the device meets the minimum OS requirement, and avoid rushing through identity or account prompts. That small amount of preparation matters more here than it would with a simple calculator because the app is intended to connect with real financial activity.
During the first launch, read each screen rather than tapping through automatically. The right choice may depend on whether you are accessing an existing Wisely arrangement or beginning the account process. If a screen asks you to confirm personal details, compare them with your records before continuing. A typo in contact information can turn a routine sign-in problem into a frustrating recovery task later.
I also recommend choosing a login method you can reliably use when you are away from home. The best setup is not the one that looks fastest; it is the one you will still be able to complete after changing phones, losing access to a temporary email address, or forgetting which detail you used. Keep any confirmation messages and account instructions somewhere safe while you are getting established.
Do not judge the app before the account connection is complete. A finance app can look empty or limited until it has the right account context. This is one of the first places where new users can become confused: they may assume that an empty activity area means the app is broken, when it may simply mean there is nothing available to display yet or that the setup path has not been finished.
Another useful habit is to decide what you want to check first. If pay is your priority, look for the area that shows incoming funds. If spending control is the reason you installed it, concentrate on recent transactions. If saving is your goal, identify the saving-related tools only after you understand the available balance. This prevents the common mistake of treating every menu item as equally important.
The first successful action I recommend
For a first-time user, I would make the first success a simple balance-and-activity check. Open the app after setup, confirm that the available amount makes sense, and review the latest visible transactions. You are not trying to build a perfect budget in the first session. You are verifying that the app reflects the financial activity you expected and learning where the information lives.
That check is more valuable than merely signing in. It answers practical questions immediately: Can I recognize the account? Do I understand the amount shown? Can I identify a recent purchase or payment? Does the activity look current enough for my needs? If the answer to those questions is yes, you have already created a dependable daily routine.
I would then make one small spending observation. Look at the last few purchases and ask whether they match what you remember. This is a concrete way to use the app’s tracking purpose instead of passively reading numbers. If you notice that several small expenses repeat during the week, that pattern may be more useful than a broad monthly guess.
A realistic example is a payday morning. I would open myWisely, check that the expected money is visible, scan the recent activity, and decide what amount is safe to use for the next few days. Later, after buying lunch and commuting home, I would check the activity again rather than relying on memory. That second glance turns the app into a habit: not a source of anxiety, but a quick confirmation that my spending is still under control.
For saving, I would begin with observation rather than an ambitious target. Watch how much remains after ordinary expenses, then choose a repeatable amount that does not make the rest of the week difficult. The important insight is that saving tools work best when they are connected to a realistic spending picture. Moving money with no awareness of upcoming needs can make an app feel restrictive, even when the underlying intention is good.
Small workflows that make the app more useful
One workflow I found useful is separating “checking” from “investigating.” A quick balance check should take only a moment. Investigating means opening activity when an amount seems unfamiliar, comparing it with a receipt or memory, and deciding whether it is simply a delayed recognition issue or something that needs attention. Keeping those actions separate stops every login from becoming an exhausting financial audit.
A second useful approach is to review spending at a consistent trigger rather than at random. Payday, the end of a work shift, or the moment you return from grocery shopping can all work. The trigger matters because memory is weakest when purchases are scattered across busy days. A short review while the context is fresh gives the transaction list more practical value than a long review weeks later.
A third trade-off concerns saving. It is tempting to treat any available saving function as a reason to move money immediately. I prefer to first account for predictable essentials and leave a comfortable margin. The app can support awareness, but it cannot know every personal obligation or irregular expense. The user still has to decide whether a saving action is sustainable.
There is also a helpful distinction between the app and a written budget. myWisely can show what happened and help you act on current information, while a separate budget may be better for planning rent, annual bills, debt payments, or shared household costs. I would not force the app to replace a system it was never designed to be. Used alongside a simple notes file or spreadsheet, it can provide the current spending view while the other tool handles longer-term planning.
Where first-time users may get confused
The biggest source of confusion is likely the difference between money that appears available and money that you have mentally assigned to upcoming obligations. A visible balance is not the same thing as “free money.” Before spending, I would think through bills, transport, food, and any commitments that are not yet reflected in the activity list.
Transaction timing can also make a screen seem surprising. A purchase may be remembered from one moment while the account display changes at another. Rather than panicking over a single unfamiliar entry, check the merchant description, amount, and surrounding activity. If something still does not make sense, keep the receipt or confirmation so you have a clear reference when seeking help.
New users sometimes expect the app to categorize every expense in exactly the way they would. Personal labels and real-world descriptions do not always line up. I would use the activity list first as a factual record, then interpret it according to my own budget. That approach avoids building a plan on assumptions about what a transaction “should” mean.
Another point worth understanding is that a focused payment app is not automatically a complete replacement for a bank. If you need services outside its central pay-and-spend purpose, you may still need another financial provider. That is not necessarily a weakness; it is a reason to define the app’s job clearly. I would use it for the tasks it makes convenient and keep a separate service for needs it does not cover.
If setup or access does not go as expected, resist the urge to create repeated accounts or change details randomly. Record the exact message, note which step produced it, and use the appropriate support route associated with the account. In financial services, careful troubleshooting is safer than experimenting. The same advice applies if a balance or transaction looks wrong: document what you see before taking action.
Privacy is another reason to treat the app thoughtfully. Since this is a finance tool, I would avoid signing in on a shared device, keep the phone protected, and be cautious about showing account screens in public. These are ordinary habits, but they matter more when an app provides access to pay and spending information.
How it compares with familiar alternatives
Compared with a traditional bank app, myWisely feels more specialized and potentially less overwhelming. A bank app may offer a broader account relationship, while this one is attractive when your immediate concern is receiving money and monitoring everyday use. The trade-off is breadth: people who want a full financial center may prefer their existing bank’s ecosystem.
Compared with a standalone budgeting app, it has a more direct connection to the money activity it is meant to display. A budgeting app may offer more elaborate planning, categories, forecasts, or manual customization, depending on the product. myWisely makes more sense when you want a practical current view rather than a detailed financial-planning project.
Compared with checking a balance through occasional alerts or paper records, the app encourages a more active routine. The advantage is visibility between paydays. The disadvantage is that frequent checking can become unhelpful if it turns into worry without a decision attached. I recommend opening it with a purpose: verify a payment, review recent spending, or decide what can safely be saved.
My recommendation after using it
I would recommend myWisely to a first-time user who wants a focused way to follow pay and spending, especially when the service fits their existing Wisely arrangement. The free entry point, straightforward purpose, and mobile access make it approachable. Its strongest value is not a flashy feature; it is the chance to replace guesswork with a quick view of current financial activity.
I would not recommend it as the only tool for someone with complex financial planning needs. Investors, households managing many shared obligations, and users who require extensive budgeting controls should compare it with a fuller bank or budgeting service. Keeping expectations realistic is the difference between finding the app useful and feeling disappointed that it does not behave like an entirely different product.
My suggested path is simple: install it on a compatible device, complete setup carefully, confirm your account context, and make the first balance-and-activity check your initial win. After that, attach reviews to real moments such as payday or grocery shopping. Use the information to make one small decision, then build from there.
With an Everyone content rating and a growing user base, the app is accessible to a wide audience, but accessibility does not remove the need for financial judgment. I like it most when it stays in its lane: helping me see what is happening now and encouraging more deliberate choices about spending and saving.
In the end, myWisely: Mobile Banking is a sensible choice for people who value a clear, mobile-first view of everyday money. It will not replace every financial service, and it may feel too limited for advanced planners, but it can make the first steps toward better money awareness feel manageable. The best result comes from using it as a regular decision tool, not merely as a place to look at a balance.
Frequently Asked Questions
01What is myWisely: Mobile Banking used for?
myWisely: Mobile Banking is designed for Wisely cardholders who want to manage their prepaid or payroll card from a phone. After signing in, users can generally review their available balance, check transaction history, receive account notifications, locate participating ATMs, and manage selected card settings. The exact tools available may depend on the type of Wisely account and the services enabled by the card provider.
02Is myWisely: Mobile Banking free to download and use?
The app is generally available to download at no upfront cost, but that does not mean every service connected with the account is free. Certain transactions, ATM withdrawals, transfers, expedited services, or other features may involve fees according to the card’s terms and conditions. Before relying on a particular function, review the fee schedule provided for your Wisely card and confirm any charges in the app.
03How do I sign in to the myWisely app if I am a new user?
To use myWisely, you normally need an eligible Wisely card or account and the personal information requested during registration. The app may ask you to verify your identity, create login credentials, and confirm a phone number or email address. Keep your card details and contact information available, and use only the official app-store version to avoid entering sensitive information into an imitation application.
04Can I use myWisely to withdraw cash and find ATMs?
The application can help eligible cardholders manage cash access by displaying ATM-location tools and account information, although availability and fees depend on the card program and the ATM network. Before making a withdrawal, check the displayed balance and review possible operator or out-of-network charges. ATM availability, withdrawal limits, and fee-free options may also vary by location and account agreement.
05What should I do if my card, phone, or account is lost or compromised?
If you suspect that your Wisely card or account has been compromised, act quickly by using the app’s available card-control or lock features, if supported, and contact official Wisely customer support through the verified website, app, or phone number. Do not share passwords, one-time codes, or full card details with unsolicited callers. If your phone is lost, secure the device and change your account credentials.


